
How Spending Needs Shift Across Life Stages: Before 40, Between 40–60, and After 60
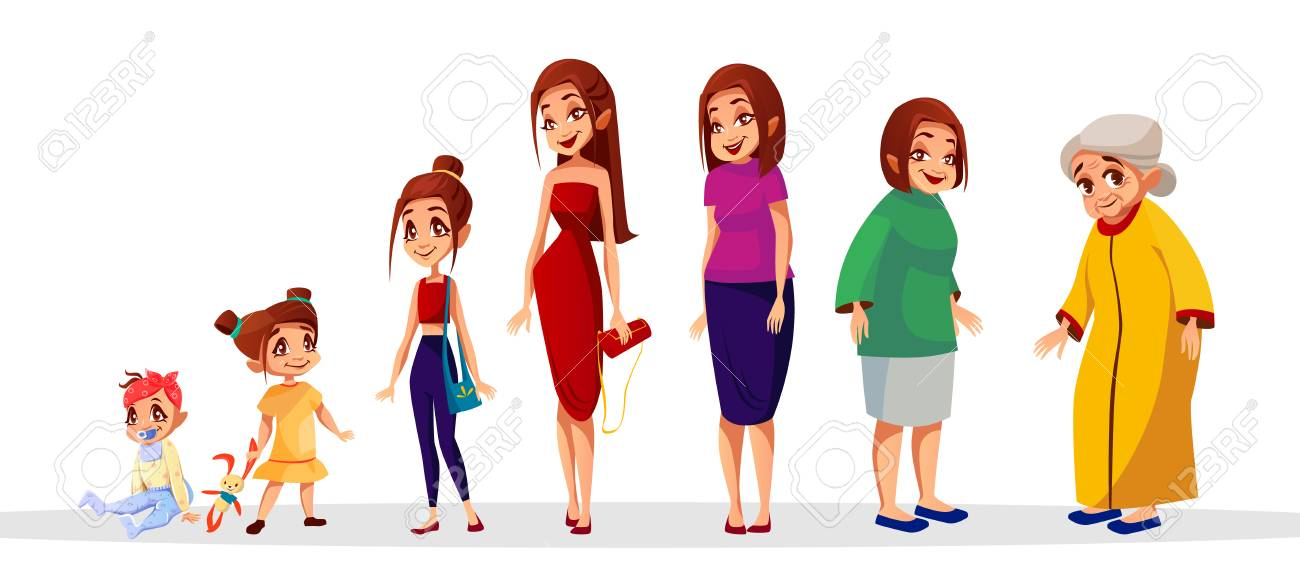
When it comes to money, one truth often gets overlooked: the way we should spend meaningfully depends a lot on our stage of life.
What matters at 25 isn’t the same as what matters at 50 or 65. Each season comes with unique opportunities, pressures, and risks. If we fail to align our money habits with the realities of these seasons, we either miss out on joy or carry regret into the future.
Let’s unpack these three stages:
Before 40: Building Identity and Discipline
Characteristics
- Energy is high, but money is tight.
- Careers are starting; income is still growing.
- Student loans, early family responsibilities, or other obligations weigh heavily.
- Identity is still being shaped — “Who am I? What do I want in life?”
Problems
- Lifestyle pressure: wanting to “catch up” with peers (cars, fashion, social status).
- Limited financial resources cause frustration.
- Easy to confuse “wants” with “needs.”
- Lack of clarity about long-term direction.
Needs
- Direction and clarity: What does a meaningful life look like?
- Disciplined spending: making limited money count.
- Building strong habits of aligning money with values.
Action Steps
- Define personal values early — decide what matters most (education, experiences, relationships, skills).
- Spend on growth — courses, skills, networking, exposure.
- Avoid peer pressure spending — create your own definition of success.
- Invest in health & habits — diet, fitness, and mental wellbeing.
Reflection Question
“What do I want my money to say about me at this stage?”
Between 40–60: The Sweet Spot Years
Characteristics
- Income stabilizes and peaks.
- Careers or businesses mature.
- Children may still be dependents.
- Greater control over choices.
Problems
- Lifestyle creep: tendency to overspend on luxuries (cars, homes, appearances).
- “Sandwich generation” pressure: supporting kids + aging parents.
- Work-life imbalance: chasing money, forgetting relationships and self.
Needs
- To strike balance: joy today + security tomorrow.
- Experiences: travel, family bonding, personal fulfillment.
- Reassessing purpose — what really matters at this point in life?
Action Steps
- Spend meaningfully — on experiences that strengthen relationships and create memories.
- Be intentional about lifestyle upgrades — don’t just buy bigger, ask if it adds real value.
- Invest in health — preventive care and wellness routines.
- Plan legacy spending — mentoring, giving back, supporting causes.
Reflection Question
“What do I want to experience in my 40s and 50s that I may not enjoy at 70?”
After 60: Simplify, Connect, and Leave a Legacy
Characteristics
- Retirement or reduced active income.
- Health concerns start to increase.
- More time freedom, but less physical energy.
- Family expands (grandchildren, extended relatives).
Problems
- Medical expenses rise.
- Relatives may lean more on you financially.
- Risk of regret if earlier years were misused.
- Loneliness or lack of purpose after active work life.
Needs
- Stability, peace, and fulfillment.
- Simplicity in lifestyle.
- Stronger relationships and social connections.
- Health support systems.
Action Steps
- Spend on relationships & connection — family time, community, friendships.
- Simplify lifestyle — less clutter, more meaning.
- Prioritize health spending — medical care, wellness, comfortable living.
- Create memories with family — storytelling, travel (where possible), bonding traditions.
- Use money for legacy — charity, causes, mentoring the next generation.
Reflection Question
“What memories and values do I want to leave behind?”
Final Thoughts
Money isn’t just for saving or investing — it’s for living meaningfully in every season of life.
- Before 40 is about building identity and discipline.
- 40–60 is the sweet spot for aligning peak income with purpose.
- After 60 is the season of simplifying, connecting, and leaving a legacy.
Whatever stage you’re in, the most important step is this: make sure your money reflects what matters most to you.
Discover more from Happy Pockets
Subscribe to get the latest posts sent to your email.